Audit, tax and advisory,
partner-led since 2018.
YSAR & Associates is an assurance-led firm of Chartered Accountants providing audit, assurance, taxation and advisory services to listed-group entities, trusts and growing businesses from offices in Bengaluru and Chennai.
An assurance-led firm, built on continuity
YSAR & Associates has been in continuous practice since 2018, carrying forward the same team, quality processes and professional relationships. From offices in Bengaluru and Chennai, we serve listed-group entities, trusts and growing businesses with partner-led engagements from planning to sign-off.
The firm's core practice is audit and assurance. Around it sit taxation, financial reporting under Ind AS and AS, certifications, risk advisory and management consulting, delivered by specialist teams with quality processes benchmarked to ICAI's Peer Review mechanism.
Our services
Audit & Assurance
Statutory audit, limited review, tax audit, transfer pricing audit, internal audit, BRSR assurance and IFC/ICoFR reporting under the Standards on Auditing.
Direct & Indirect Tax
Income tax including expatriate and DTAA matters, GST, and TDS/TCS compliance — from filings to assessment and appellate representation.
Advisory & Outsourcing
SEBI ICDR and regulatory certifications, Ind AS/IFRS conversion, IPO readiness, risk advisory, management consulting, virtual CFO and accounting outsourcing.
From boutique practice to multi-city firm
Established as S P Rajesh & Co. — a boutique assurance practice with a 3-member team.
Re-constituted as a partnership; S Yogarathanam joins as partner. Team grows to 8 members.
Becomes an ICAI peer-reviewed firm; internal audit practice added.
Investment in audit technology; virtual CFO and outsourced accounting launched; multi-city presence established.
Advisory practice launched — consulting, IFC and Ind AS. Team grows to 12 members.
Pandiyan Shanmugakani and Asha Raj Pradeep join as partners; capital-market certifications added.
Reconstituted as YSAR & Associates — a 15-member firm across Bengaluru and Chennai.
What we do
Partner-led delivery across assurance, taxation and specialist advisory services.
Select a service to view its scope
Our core practiceAudit & Assurance
Statutory Audit
Companies Act, 2013+
Audit of financial statements under the Companies Act 2013, conducted under the Standards on Auditing.
- Statutory audits with reporting under CARO 2020
- Audit of branches and components
- Communication with those charged with governance
Limited Review
SRE 2410+
Interim financial reviews of listed-group entities under SRE 2410.
- Quarterly limited reviews
- Interim reporting support on listed-entity timetables
Tax Audit
Sec 44AB · Form 3CD+
Tax audit under Section 44AB with clause-wise reporting in Form 3CD.
- Form 3CA/3CB and 3CD reporting
- Clause-wise documentation of positions
Transfer Pricing Audit
Sec 92E · Form 3CEB+
Reporting in Form 3CEB on international and specified domestic transactions.
- Form 3CEB certification
- Documentation review and coordination with TP studies
Internal Audit
Sec 138+
Risk-based internal audit for companies and groups.
- Internal audit under Section 138
- Process reviews and SOP construction
- Compliance diagnostic reviews
BRSR Assurance
SEBI LODR+
Assurance on Business Responsibility and Sustainability Reporting under SEBI LODR.
- Reasonable and limited assurance on BRSR Core
- BRSR certification held since 2023
- ESG data validation
IFC / ICoFR Reporting
Sec 143(3)(i)+
Reporting on internal financial controls over financial reporting, with design and documentation support.
- Reporting under Section 143(3)(i)
- Risk-and-control matrix design and walkthroughs
- Remediation support
Certifications
SEBI · Tax · Bank · MCA+
Certifications for capital-market, tax, banking and regulatory purposes.
- SEBI ICDR (ICA) certifications for IPOs
- Tax certifications: Form 146, 165, 3CEAA, 3CEFA
- Bank certifications: debt covenant & loan end-use
- MCA form certifications: DPT-3, AOC-4, MGT-7
Compliance & representationTaxation
Income Tax
Direct tax+
Compliance and advisory for companies, firms and individuals.
- Corporate and individual return preparation and filing
- Expatriate taxation and DTAA relief
- Diagnostic tax health-check reviews
- Assessment and appellate representation
Goods & Services Tax
Indirect tax+
End-to-end GST compliance and representation.
- Registrations and periodic returns
- ITC reconciliation (2B vs books)
- Refunds, notices, audits and representation
TDS / TCS
Withholding compliance+
Withholding tax compliance across payroll and vendor payments.
- Quarterly returns (24Q / 26Q / 27Q)
- Form 16 / 16A issuance
- Defaults resolution on TRACES
- Lower-deduction applications
Beyond the auditAdvisory & Outsourcing
Accounting Advisory
Ind AS · IFRS+
Technical accounting and financial reporting support.
- Consolidated financial statements preparation
- GAAP transition — Ind AS / IFRS
- Accounting position papers
IPO Readiness
Capital markets+
Preparing companies for the listing process.
- Financial statements and restatement support
- Readiness diagnostics and gap remediation
- Coordination with intermediaries
Agreed-Upon Procedures
SRS 4400+
Factual findings on specified financial information.
- Receivables & payables analysis
- Vendor / customer master accuracy
- Fixed asset register & leasing data
Management Consulting
Advisory+
Finance-function support for growing businesses.
- Audit support & PBC / IRL response preparation
- Co-sourcing & financial due diligence
- Business plans, cash-flow projections & budgets
Virtual CFO
Outsourced finance+
An outsourced finance function, sized to the business.
- MIS reporting and dashboards
- Budgeting and variance analysis
- Finance process and SOP development
Accounting Outsourcing
Compliance-ready books+
Bookkeeping and compliance services that keep records audit-ready.
- Bookkeeping, reconciliations, AP / AR
- Payroll outsourcing
- GST & TDS compliance, ITR filing
How we audit
A risk-based approach under the Standards on Auditing — planned around your business, executed with data, concluded by partners.
Plan & Scope
Understand the business and its environment; set materiality; agree timelines and information needs up-front.
Assess Risk
Identify risks of material misstatement; walk through key controls; apply a professional-scepticism and fraud lens.
Execute
Substantive testing driven by data analytics and statistical sampling; full-population checks where they add assurance.
Report & Conclude
Independent partner review; clear communication with those charged with governance; timely opinion.
STANDARDS ON AUDITING (ICAI) · INDEPENDENCE & CODE OF ETHICS · SQC 1 DOCUMENTATION · PEER REVIEW CERTIFIED · TECHNOLOGY-ENABLED AUDIT TOOLS
The partners behind the opinion
Three practising Chartered Accountants lead the firm's assurance, tax and advisory practices, supported by 15+ audit staff and article assistants across Bengaluru and Chennai.
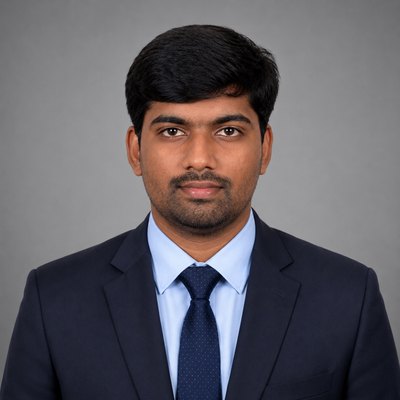
S Yogarathanam
Managing Partner · Assurance HeadChartered Accountant specialising in statutory audits and SEBI ICDR capital-market certifications. Leads the firm's assurance practice and Bengaluru operations.
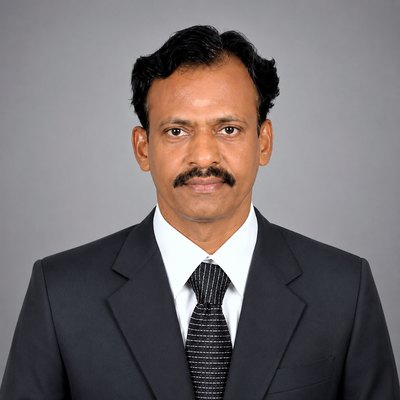
PASS Pandiyan Shanmugakani
Partner · Tax HeadChartered Accountant with 37+ years in direct taxation and bank audits. Formerly Partner at Ponraj & Co. (2006–2024).
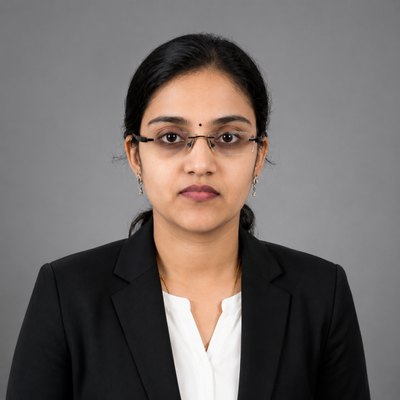
Asha Raj Pradeep
Partner · Advisory HeadChartered Accountant specialising in corporate accounting, Ind AS convergence and internal audits.
Beyond the partners
Our team includes qualified Chartered Accountants, CA finalists, article assistants and experienced accounting professionals — with structured training and second-partner review before any listed-group or higher-risk opinion is signed.
Notes on tax, audit & reporting
Short, practical updates from our team on regulatory change and financial reporting — written for promoters, CFOs and finance teams.
ITR filing for AY 2026-27: what has changed this season
Staggered due dates, expanded form eligibility and revised disclosure fields — alongside one structural point that is easy to get wrong.
This filing season carries a distinction that will not repeat. The Income-tax Act, 2025 came into force on 1 April 2026, but the return being filed now relates to income earned in FY 2025-26 — a period beginning before that date. Assessment Year 2026-27 is therefore governed entirely by the Income-tax Act, 1961: the forms, the sections, the late fee under Section 234F, and any defective-return notice under Section 139(9).
In practical terms, this is the last regular filing season under the 1961 framework. Returns for income earned from April 2026 onwards fall under the new Act and are not due until 2027.
Drafting point: any client note, submission or representation for AY 2026-27 should continue to cite the 1961 Act. Citing the 2025 Act this year is a substantive error, not a stylistic one.
Due dates are no longer a single date
The Finance Act, 2026 amended Section 139(1) to give non-audit taxpayers filing ITR-3 and ITR-4 a due date of 31 August, in place of the common 31 July. This is a permanent statutory change effective from AY 2026-27 — not the kind of last-minute extension the profession has grown used to waiting for.
- 31 July 2026 — ITR-1 and ITR-2 (salary, house property, capital gains, other sources)
- 31 August 2026 — ITR-3 and ITR-4 where the taxpayer is not subject to tax audit
- 31 October 2026 — audit cases, with the audit report due one month earlier
The revised return window under Section 139(5) closes on 31 March 2027.
Forms notified early
The CBDT notified ITR-1 to ITR-7 on 30 March 2026 through the Income-tax (Sixth Amendment) Rules, 2026 — considerably earlier than the late-April notification of the previous year. The filing window has been open since the start of the season, which is worth using: early filing reduces exposure to portal congestion and speeds up refunds.
Changes worth noting before you file
- Two house properties in ITR-1 and ITR-4. Eligibility has been widened; taxpayers previously pushed into ITR-2 for a second property may now file the simpler form.
- Schedule AL threshold raised. Assets and liabilities reporting now applies where total income exceeds ₹1 crore.
- Section 80G donations. The bank IFSC code and transaction reference number must now be reported for the deduction claim.
- Capital gains. The pre- and post-23 July 2024 rate split has been removed for AY 2026-27. Long-term capital gains disclosure has been expanded, including grandfathering and indexation details and scrip-level reporting for equity.
- F&O and intraday. Separate reporting fields have been introduced, which makes the classification between business income and capital gains harder to leave ambiguous.
Where returns actually go wrong
Two failure modes account for most of the trouble we see. The first is form selection: a return filed on the wrong form is treated as defective under Section 139(9), attracting a notice and a refiling. A salaried individual with a consultancy stream or a trading account belongs in ITR-3, not ITR-1, however simple the salary looks. Partners and their firms file separately — ITR-3 and ITR-5 — and those two filings must agree with each other.
The second is AIS and TIS reconciliation. With expanded scrip-level and derivative reporting, prefilled data is now detailed enough that unexplained differences surface quickly. Reconciling the Annual Information Statement against books before filing — rather than after a notice arrives — remains the single highest-return hour in the process.
This article reflects the position as at the date of publication and is provided for general information only. It does not constitute professional advice. Specific advice should be obtained before acting on any part of it.
The Invoice Management System is now mandatory
From 1 April 2026, what appears in your GSTR-2B depends on what you did on the IMS dashboard — or failed to do.
The Invoice Management System has been available on the GST portal since late 2024, and for most businesses it was quietly ignored. That is no longer an option. From 1 April 2026, IMS applies to all regular registered persons filing GSTR-3B; taxpayers under the composition scheme are outside it.
The shift matters because IMS now sits upstream of GSTR-2B. Records no longer flow automatically from the supplier's GSTR-1 into your credit statement. They land on your IMS dashboard first, and only what you accept — expressly or by default — becomes available credit.
How the flow now works
A supplier files GSTR-1, the IFF, or an amendment through GSTR-1A. Those records appear on the recipient's IMS dashboard, where three actions are available:
- Accept — the record flows into GSTR-2B as available ITC and auto-populates GSTR-3B.
- Reject — the record is excluded from GSTR-2B. The supplier is notified and can amend or cancel in GSTR-1.
- Pending — the record is held back from GSTR-2B and stays on the dashboard until actioned in a later period.
Taking no action results in deemed acceptance. For genuine invoices that is harmless. For a wrongly-issued or fraudulent invoice raised against your GSTIN, it is precisely the failure mode the system was designed to prevent — and inaction hands the credit straight into your return.
The date that governs everything is the 14th. GSTR-2B is generated on the 14th of the month. Act before it. If any action is taken on or after the 14th, you must click Recompute GSTR-2B — otherwise the earlier draft remains on screen and gets used for GSTR-3B.
Constraints worth knowing before month-end
- There is no partial acceptance. An invoice is accepted or rejected in full. Accepting a wrong-value invoice intending to adjust later is not a workable plan.
- Actions lock once GSTR-3B is filed for that period. Anything missed moves to the next cycle.
- Sequence matters. Acting on an amendment before the original record, where the two fall in different return periods, is blocked by the portal — and reconciliation then fails silently.
- Credit notes now ask whether ITC needs reducing. Declare the exact amount availed and reverse only that; where the answer is partial or nil, remarks are mandatory.
What does not pass through IMS
Not every credit is routed through the dashboard, and assuming otherwise creates phantom differences during reconciliation. ISD distributions appear in GSTR-2B directly. Import of services flows straight through, as do inward supplies liable to reverse charge reported by the supplier. Bills of Entry for imports of goods, including from SEZs, have appeared on IMS since the October 2025 tax period.
A workable monthly routine
With the portal now applying hard blocks on credit claimed in excess of GSTR-2B, the reconciliation cannot be left to year-end. A short, disciplined cycle handles most of it:
- Scan the IMS dashboard around the middle of the month, before the 14th.
- Reject anything that does not correspond to a purchase you recognise — check the supplier's registration status where a record looks unfamiliar.
- Match GSTR-2B against the purchase register line by line, not in total.
- Recompute GSTR-2B if any action was taken late, then file GSTR-3B.
Businesses under QRMP can run the same rhythm fortnightly. The objective is unchanged from the pre-IMS era — credit that is genuine, matched and documented — but the point of control has moved earlier in the month.
This article reflects the position as at the date of publication and is provided for general information only. It does not constitute professional advice. Specific advice should be obtained before acting on any part of it.
BRSR Core: the top 500 are in scope now
SEBI softened several edges of the ESG reporting framework through 2024 and 2025. Read as a reprieve, that is a costly misreading.
The assurance obligation on BRSR Core has been phased in by market capitalisation, measured as at 31 March. The top 150 listed entities came into scope for FY 2023-24, the top 250 for FY 2024-25, the top 500 for FY 2025-26, and the top 1,000 for FY 2026-27. The framework sits under Regulation 34(2)(f) of the LODR Regulations.
For an entity in the top 500 band, the disclosures as at 31 March 2026 are already inside the verification net. This is a present obligation, not a horizon.
What the easing did and did not do
SEBI spent much of 2024 and 2025 moderating the harder edges of the framework. The terminology moved to “assessment or assurance”. Value chain ESG disclosure was changed from comply-or-explain to voluntary by the circular of 28 March 2025, and mandatory value chain assurance was deferred.
None of that touches the Core. The nine BRSR Core attributes — spanning greenhouse gas emissions, water, waste, energy, gender diversity, wages, inclusive development, fairness in engaging with customers, and openness of business — remain subject to independent verification on the phased schedule. The Industry Standards on BRSR Core reporting, developed by the Industry Standards Forum and notified in December 2024, standardised the definitions, which in practice raises rather than lowers the evidential bar.
Why reasonable assurance is different. It calls for larger samples, testing of the controls around the data, and a positive opinion on reliability — not the negative form of conclusion that limited assurance permits. ESG data pipelines built for disclosure rarely survive that standard without work.
Where readiness usually fails
The gaps we encounter are consistent, and none of them are technical accounting problems:
- No named owner for a KPI. The classic discovery, three weeks before fieldwork, is that nobody actually owns the water number.
- Manual collection with no audit trail. A figure assembled from plant emails cannot be re-performed.
- Undocumented emission factors. The source and vintage of each factor must be evidenced, and the same rate used for the current and comparative year.
- Inconsistent output measures. Intensity ratios need a defensible denominator — for manufacturing entities, total production.
- No internal control layer. Data ownership and a sign-off ladder should exist before the assurance provider arrives, not in response to their queries.
Practical steps for the coming cycle
- Confirm your cohort against 31 March market capitalisation, and monitor rank if you sit near a band boundary.
- Assign a named owner and a documented methodology to each Core attribute.
- Freeze emission factors and output measures, and record the basis in writing.
- Run an internal dry run on the data pipeline — effectively an internal audit of the ESG numbers — well ahead of the engagement.
- Brief the audit committee on provider independence and on its own role in the integrity of the filed BRSR Core.
Entities in the top 1,000 band come into scope for FY 2026-27. The year in hand is the one in which the plumbing gets built quietly, or does not.
This article reflects the position as at the date of publication and is provided for general information only. SEBI’s requirements continue to evolve; current obligations should be confirmed against the applicable circulars. This does not constitute professional advice.
Speak to the firm
Write to us or visit either office.
RMV II Stage, Sanjaynagar
T2, Panchajanya Apartments, 119 AG's Layout,RMV II Stage, Sanjaynagar,
Bengaluru – 560 094, Karnataka
☎ +91 75029 59907 · 080-4114 0644
✉ info@caysar.in · yogesh@caysar.in
Tondiarpet
No 49/66, Senniyamman Koil Street,Tondiarpet,
Chennai – 600 081, Tamil Nadu
✉ info@caysar.in
Prefer email? Write directly to info@caysar.in.